International Tax Invoice Rules: US, UK VAT, EU & Canada GST/HST
An international tax invoice is an official billing record showing your registered tax identification number, supply date, customer details, taxable vs. non-taxable line items, applicable tax rates (Sales Tax, VAT, or GST/HST), and statutory reverse-charge or exemption wording required by tax authorities in the buyer's or seller's jurisdiction.
Freelancers, SaaS consultants, and small agencies regularly lose weeks of cash flow when a European or Canadian accounts payable team rejects an invoice missing a VAT registration ID, an HMRC "tax point" date, or reverse-charge text. Start with a structured tax invoice template and verify every mandatory rule across the US, UK, EU, and Canada below. (Note: tax thresholds and exemptions change by statute and business entity; verify specific edge cases with a licensed CPA or chartered tax advisor.)
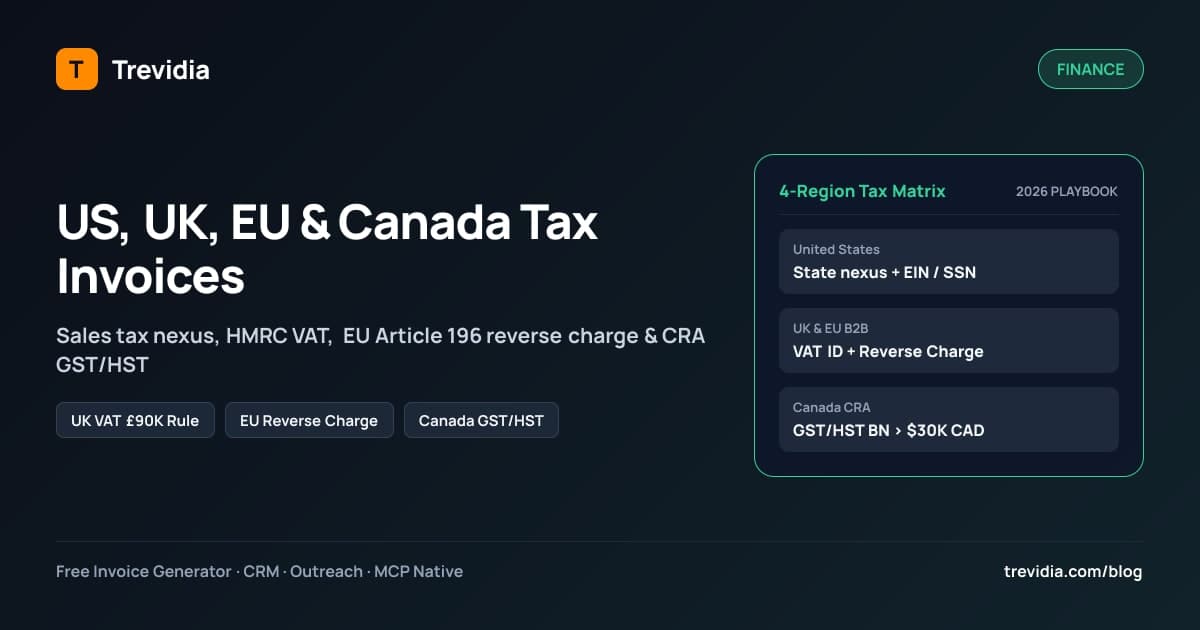
4-Jurisdiction Tax Invoice Compliance Matrix
Compare the core tax-invoice requirements side by side before billing domestic or cross-border B2B clients:
| Requirement | United States (Sales Tax) | United Kingdom (HMRC VAT) | European Union (Cross-Border B2B) | Canada (CRA GST/HST) |
|---|---|---|---|---|
| Primary Tax System | State, county & city Sales Tax (no federal VAT) | Value Added Tax (20% standard, 5% reduced, 0% zero) |
Harmonized EU VAT (Directive 2006/112/EC) |
Federal GST (5%), combined HST (13%–15%), plus QST/PST in QC/BC/SK/MB |
| Mandatory Registration Threshold | Physical nexus OR economic nexus (often $100,000 sales or 200 transactions/state) |
£90,000 rolling 12-month taxable turnover |
Local domestic thresholds vary; €0 on many non-resident cross-border B2B/B2C rules |
$30,000 CAD over 4 consecutive quarters (small supplier threshold) |
| Required Seller Tax ID | State Sales Tax Permit ID (EIN/SSN kept internal on W-9, not required on every B2B invoice) | 9-digit GB VAT Number (GB 123 4567 89) |
EU VAT Identification Number (e.g., DE..., IE..., FR...) |
9-digit CRA Business Number + RT0001 |
| Required Buyer Tax ID | Exemption/Resale certificate number if tax-exempt | Required for cross-border / reverse-charge domestic construction (CIS) | Mandatory buyer VAT ID validated via VIES for 0% B2B Reverse Charge | Mandatory when invoice total is $100 CAD or more (for buyer input tax credits) |
| Required Date Fields | Invoice issue date & payment due date | Issue Date AND Supply / Tax Point Date (if different) | Issue date & supply/completion date (or payment date if earlier) | Date of invoice (or date tax becomes payable) |
| Invoice Labeling | "Invoice" | Must clearly display VAT breakdown | Must show Reverse Charge or local VAT breakdown |
Tax status per item (GST/HST included or separated) |
For deeper US-specific invoice basics—including EIN handling and W-9 workflows—check our companion guide on what needs to be on a US invoice.
1. United States: State Nexus, Taxable Services & W-9 Separation
Unlike the UK, EU, and Canada, the United States imposes no federal VAT or GST. Instead, 45 states plus Washington, D.C. administer state and local sales taxes—each with distinct rules on whether SaaS, digital downloads, design, or consulting services are taxable.
Key US Tax Invoice Rules
- Verify economic nexus and service taxability: Most pure professional services (strategy consulting, custom legal/accounting advice, custom copywriting) remain non-taxable in many states, while SaaS, canned software, digital products, and certain installation or creative production services are taxable in states like Texas, New York, Washington, and Pennsylvania once you cross state nexus thresholds (commonly
$100,000in annual sales or 200 transactions, though several states removed the 200-transaction count). - Separate taxable vs. non-taxable line items: If a single invoice bundles
$4,000in tax-exempt consulting with$1,000in taxable hardware or digital software seats, list them on separate lines and mark tax status clearly. Bundling both into one line often forces tax across the whole$5,000sum. - Show state/local tax rates cleanly: Display the state rate and local jurisdiction tax (or combined effective rate) separately from the subtotal.
- Keep SSNs off client PDFs: Corporate US clients need a signed IRS Form W-9 for 1099-NEC reporting, not your Social Security Number printed in plain text on every PDF invoice. Use an EIN on vendor onboarding forms and keep public invoice headers clean.
2. United Kingdom: HMRC Full vs. Simplified vs. Export VAT Invoices
Once your UK taxable turnover exceeds £90,000 in any rolling 12-month period (or you expect to cross £90,000 in the next 30 days alone), HMRC requires VAT registration and compliant VAT invoices within 30 days of the tax point.
Mandatory Elements on a Full UK VAT Invoice
Under HMRC VAT Notice 700, a full VAT invoice must display:
- Sequential, unique identifying invoice number (zero gaps)
- Seller's legal business name, address, and GB VAT registration number
- Customer's legal name (or trading name) and address
- Invoice issue date AND Time of Supply (Tax Point) if different
- Description identifying the goods/services, quantity, unit price excluding VAT, and rate of any cash discount
- Total amount excluding VAT, rate and amount of VAT charged at each rate (
20%,5%,0%), and total payable including VAT
Simplified & Modified VAT Invoices: For retail supplies under £250 (including VAT), HMRC permits a simplified invoice omitting customer details and showing the VAT-inclusive total plus applicable VAT rate.
Billing Outside the UK (US, EU, Rest of World B2B): When a UK VAT-registered agency supplies general B2B consulting or software services to a business established outside the UK (for example, a New York LLC or a Berlin GmbH), the Place of Supply is generally where the customer belongs—making the supply outside the scope of UK VAT. Do not charge 20% UK VAT; verify business status (company registration number, business domain, or VAT ID) and mark the line item Outside scope of UK VAT — B2B place of supply rules.
3. European Union: Cross-Border B2B Reverse Charge & VIES Verification
If your business is VAT-registered in an EU Member State (say Ireland, Germany, or the Netherlands) and invoices a VAT-registered B2B client in another EU Member State, do not charge your domestic VAT rate—and do not manually charge their country's VAT rate on general B2B services.
Instead, apply the EU Reverse Charge Mechanism under Article 196 of EU VAT Directive 2006/112/EC:
- Validate the buyer's EU VAT ID before sending: Look up the client's VAT number in the European Commission's official VIES (VAT Information Exchange System) and save a dated PDF/screenshot of the valid consultation result as audit proof.
- Display both VAT IDs clearly: Print your own EU VAT number and the customer's verified EU VAT number on the invoice header.
- Apply
0%VAT on the invoice total: Bill net fees without adding VAT, shifting the accounting responsibility to the buyer's domestic VAT return. - Add the mandatory Reverse Charge text: Without the exact legal legend, local tax auditors can disallow zero-rating and assess unpaid VAT plus penalties against you as the supplier.
Copy-Paste EU Reverse Charge Footer: VAT Reverse Charge — Supply subject to Reverse Charge pursuant to Article 196 of Council Directive 2006/112/EC. Customer to account for VAT in Member State of establishment.
(Note: Physical goods exports outside the EU or digital B2C sales to EU consumers under OSS — One Stop Shop follow separate customs/destination VAT rules; pair physical shipments with a commercial invoice template.)
4. Canada: CRA GST/HST Tiered Rules & Provincial Taxes
The Canada Revenue Agency (CRA) ties mandatory GST/HST invoice fields directly to the total invoice value—and applies different rates across provinces (5% GST in Alberta/BC/Manitoba/Saskatchewan/Quebec, 13% HST in Ontario, 15% HST in Atlantic provinces):
| Invoice Total (Before Tax) | Mandatory CRA Disclosure on Invoice |
|---|---|
Under $30 CAD |
Supplier name/trading name, invoice date, and total amount paid/payable |
$30 CAD to $99.99 CAD |
All above plus supplier's CRA Business Number (123456789 RT0001) and total GST/HST charged (or statement that GST/HST is included and exact rate) |
$100 CAD or more |
All above plus buyer's name/trading name, brief description of supplies, and payment terms |
Small Supplier Exception: If your worldwide taxable revenues sit at or below $30,000 CAD over four consecutive calendar quarters, do not charge GST/HST unless you voluntarily register—and never print a fake tax number on a freelance invoice template.
Zero-Rated Exports From Canada: Canadian VAT/GST registrants billing B2B clients outside Canada (for example, US or UK companies receiving consulting services consumed abroad) generally treat the supply as zero-rated (0% GST/HST) while still retaining full Input Tax Credits (ITCs) on Canadian business expenses. Print "Zero-rated export of services — customer located outside Canada" alongside the client's non-Canadian billing address. (Check provincial QST in Quebec or PST rules in BC/SK/MB separately if delivering physical goods or locally sourced digital software.)
Handling Multi-Currency Invoices When Your Tax Return Is Domestic
Billing a London client in GBP or a Toronto client in CAD while filing domestic taxes in USD or EUR introduces FX compliance rules most freelancers miss:
- UK & EU Rule: Even when an invoice is issued and paid in
USD, HMRC and most EU tax authorities require the total VAT amount payable to be converted and displayed in local functional currency (GBPorEUR) on the invoice using an approved daily central bank or HMRC/ECB rate on the tax point date. - Clean Invoice Workaround: Keep line items and customer payment totals in the buyer's agreed currency (
USD $5,000.00), then add one crisp line in the invoice footer showing the official exchange rate and converted VAT equivalent (e.g.,Reference ECB Rate 1.0850 — VAT €0.00 Reverse Charge). - Sync FX gains/losses properly: When QuickBooks Online or your accounting ledger receives
$5,000on invoice issue day and settles a different domestic currency amount 15 days later, book the spread to Realized Foreign Exchange Gain/Loss rather than altering the billed invoice price.
Make sure you capture every deductible cross-border software, banking, and accounting expense before quarterly tax filings using our freelancer tax deductions checklist.
Standardize Multi-Tax Invoicing & QuickBooks Sync in Trevidia
Manually updating tax headers, currency symbols, VAT footers, and tax rates inside static Word docs invites compliance errors every time you add a client in a new country. Trevidia streamlines multi-region billing from one workspace starting on our $0/month Free Core OS:
- Configure default and per-invoice taxes: Define regional tax rates (
UK VAT 20%,Ontario HST 13%,TX Sales Tax 8.25%, or0% Reverse Charge) and tax registration numbers once, then apply or override them cleanly per invoice. - Switch currencies per client cleanly: Issue invoices in USD, GBP, EUR, CAD, or dozens of global currencies without duplicating company profiles.
- Include legal reverse-charge & export footers: Save boilerplate compliance clauses (such as EU Article 196 Reverse Charge notes) in invoice terms so cross-border B2B clients approve invoices on first pass.
- Sync directly to QuickBooks Online: Upgrade to Invoicing Pro ($9/month) on modular Trevidia pricing to automate recurring retainers, unlock Editorial agency templates, collect 3D-Secure card payments protected by 7–14 day escrow holds, and sync customers, line items, taxes, and settled payments two-way with QuickBooks Online.
Ready to stop guessing cross-border tax rules? Launch your free Trevidia workspace or download a clean tax invoice template today.
Cross-Border Tax Invoice Pre-Send Checklist
- Verified seller tax registration status (
Sales Tax Permit,GB VAT,EU VAT, orCRA BN) before applying any tax line. - Validated client's VAT/GST ID (via VIES for EU B2B reverse charge) and saved verification proof.
- Sequential invoice number contains zero gaps in your statutory tax invoice register.
- Tax Point / Supply Date listed explicitly alongside Issue Date (mandatory for UK/EU VAT).
- Taxable and non-taxable/exempt line items separated cleanly on distinct rows.
- Statutory export, zero-rate, or Article 196 Reverse Charge wording included in the footer when charging
0%. - Functional domestic currency conversion shown alongside foreign-currency VAT totals where local rules require it.